California FAIR Plan: Coverage Gaps, Discounts & How to Get Out
The FAIR Plan is often the last-resort fire policy after admitted carriers non-renew, not a full rebuild plan. If you’re on it or headed there, documented mitigation is how you change your property’s story.
- A professional wildfire risk assessment
- A clear Zone 0 (the first five feet)
- Ember-resistant vents and roof edges
- Seasonal spray or an installed defense system
- Photos, invoices, and dated records
FAIR Keeps You Covered. It May Not Rebuild Your Home.
The California FAIR Plan is the state’s insurer of last resort. It steps in when admitted carriers won’t write or renew a policy, but it’s mainly fire coverage, and its limits may fall short of what a Southern California home costs to rebuild. Many owners pair it with a separate difference-in-conditions (DIC) policy.
Ember Pro doesn’t sell insurance. We make your property safer and give you the paper trail brokers and underwriters can review.
How Ember Pro Helps FAIR Plan Homeowners
Understand Your Coverage Gap
FAIR dwelling limits can leave a big rebuild gap. Ask your broker how your limit compares to replacement cost and whether a DIC policy makes sense.
Discounts & Credits
FAIR has recognized certain mitigation measures in its pricing. What qualifies and what it’s worth are set by FAIR and can change, so keep records and ask your broker.
Mitigation That Shows
Zone 0 cleanup, home hardening, seasonal spray, and a remotely activated defense system are the kinds of work insurers often look for.
See home hardening →Documentation That Travels
You get dated photos, scope notes, and install or application records you and your broker can use when you re-shop.
A Path Back to an Admitted Carrier
Mitigation documentation can help when you re-shop with a broker. It doesn’t auto-approve a policy, but it gives underwriters more to work with.
Wildfire insurance guide →Ready at Every Renewal
Keep Zone 0 clear and your spray or system records current, so your file is ready before the next underwriting window.
Just Got a Non-Renewal Letter?
Don’t wait for Red Flag season. The sooner you start, the more you’ll have to show when you re-shop coverage.
- Book a free satellite review of your property
- Walk through your policy timeline on a Zoom call
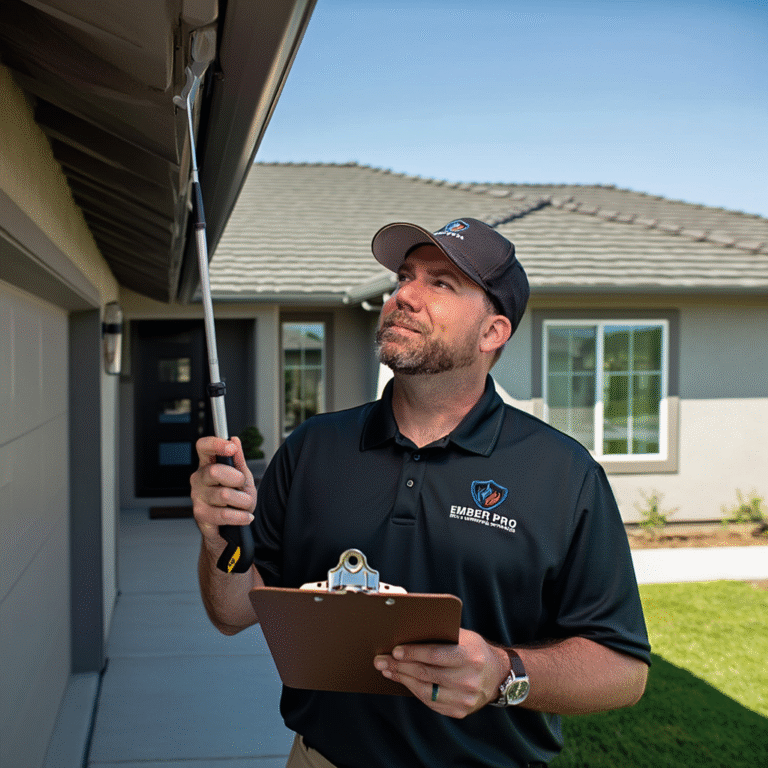
- Get an insurance-ready on-site assessment
- Complete the highest-impact fixes first
- Hand your broker a clean documentation package
We’re Contractors, Not Agents
Ember Pro is a CSLB-licensed wildfire mitigation contractor. We scope, build, and document the defenses. You place coverage with a licensed insurance professional.
From FAIR Plan to a Stronger File
-
Satellite Review
Exposure context before you talk to a broker.
-
Zoom Call
Your options: stay on FAIR, add DIC, or re-shop.
-
Insurance-Ready Assessment
Zone 0, vents, roof, attachments, and paperwork gaps.
-
Mitigate & Document
Hardening, Zone 0, spray, or a defense system, with records.
Give Your Broker Something to Work With
Book a free insurance-ready assessment. We’ll review your property by satellite first, then map the mitigation that can help when you re-shop coverage.
What Is the California FAIR Plan?
The California FAIR Plan is a state-mandated insurance pool that offers basic fire coverage to property owners who can’t get a policy from an admitted insurer, which is common in wildfire-prone areas. It’s meant as a safety net, not a complete homeowners policy, so many owners add a difference-in-conditions (DIC) policy for liability, theft, and other gaps. Documented wildfire mitigation can help when you re-shop coverage with a broker.
California FAIR Plan FAQ
Is the FAIR Plan the same as homeowners insurance?
No. It’s mainly fire coverage. Many owners add a DIC policy so theft, liability, and other losses aren’t left uncovered.
Can mitigation get me off the FAIR Plan?
It can help. Documented hardening, Zone 0 work, spray, or a defense system gives your broker a stronger submission, but carriers make the final decision.
Does the FAIR Plan offer discounts for home hardening?
FAIR has recognized certain mitigation measures, but the categories and amounts are set by FAIR and can change. We can’t promise a discount. We can document your work so you and your broker can ask.
Does Ember Pro sell insurance?
No. We’re a licensed contractor. We handle the property and the paperwork, and licensed insurance professionals handle the policy.
Reviewed by Ember Pro, CSLB #1142407 · Licensed wildfire mitigation contractor founded in Fallbrook, serving San Diego, Los Angeles, Orange, and Riverside counties.